
Low Mileage Car Insurance for Seniors in Vermont
Vermont insurers will often discount your policy for driving less, but you have to tell them your actual mileage and ask.
Yes, if you can show your insurer how little you drive
Vermont doesn't require any insurer to offer a low mileage discount, but most do, and it's one of the more common discounts for drivers who've retired or cut back on commuting. The discount is tied to how many miles you drive in a year, not your age directly. Age matters here mostly because retirement tends to mean fewer miles, not because insurers give the discount for being a certain age.
To get it, your insurer needs a mileage figure, usually an estimate you give them or a number they confirm through your odometer reading at renewal. Some companies set a mileage threshold you need to fall under. Others use telematics or odometer checks instead of asking you to guess. Call your insurer or your agent and ask directly how they calculate it and what counts as low mileage for their policies.

How your insurer verifies your mileage changes what you get
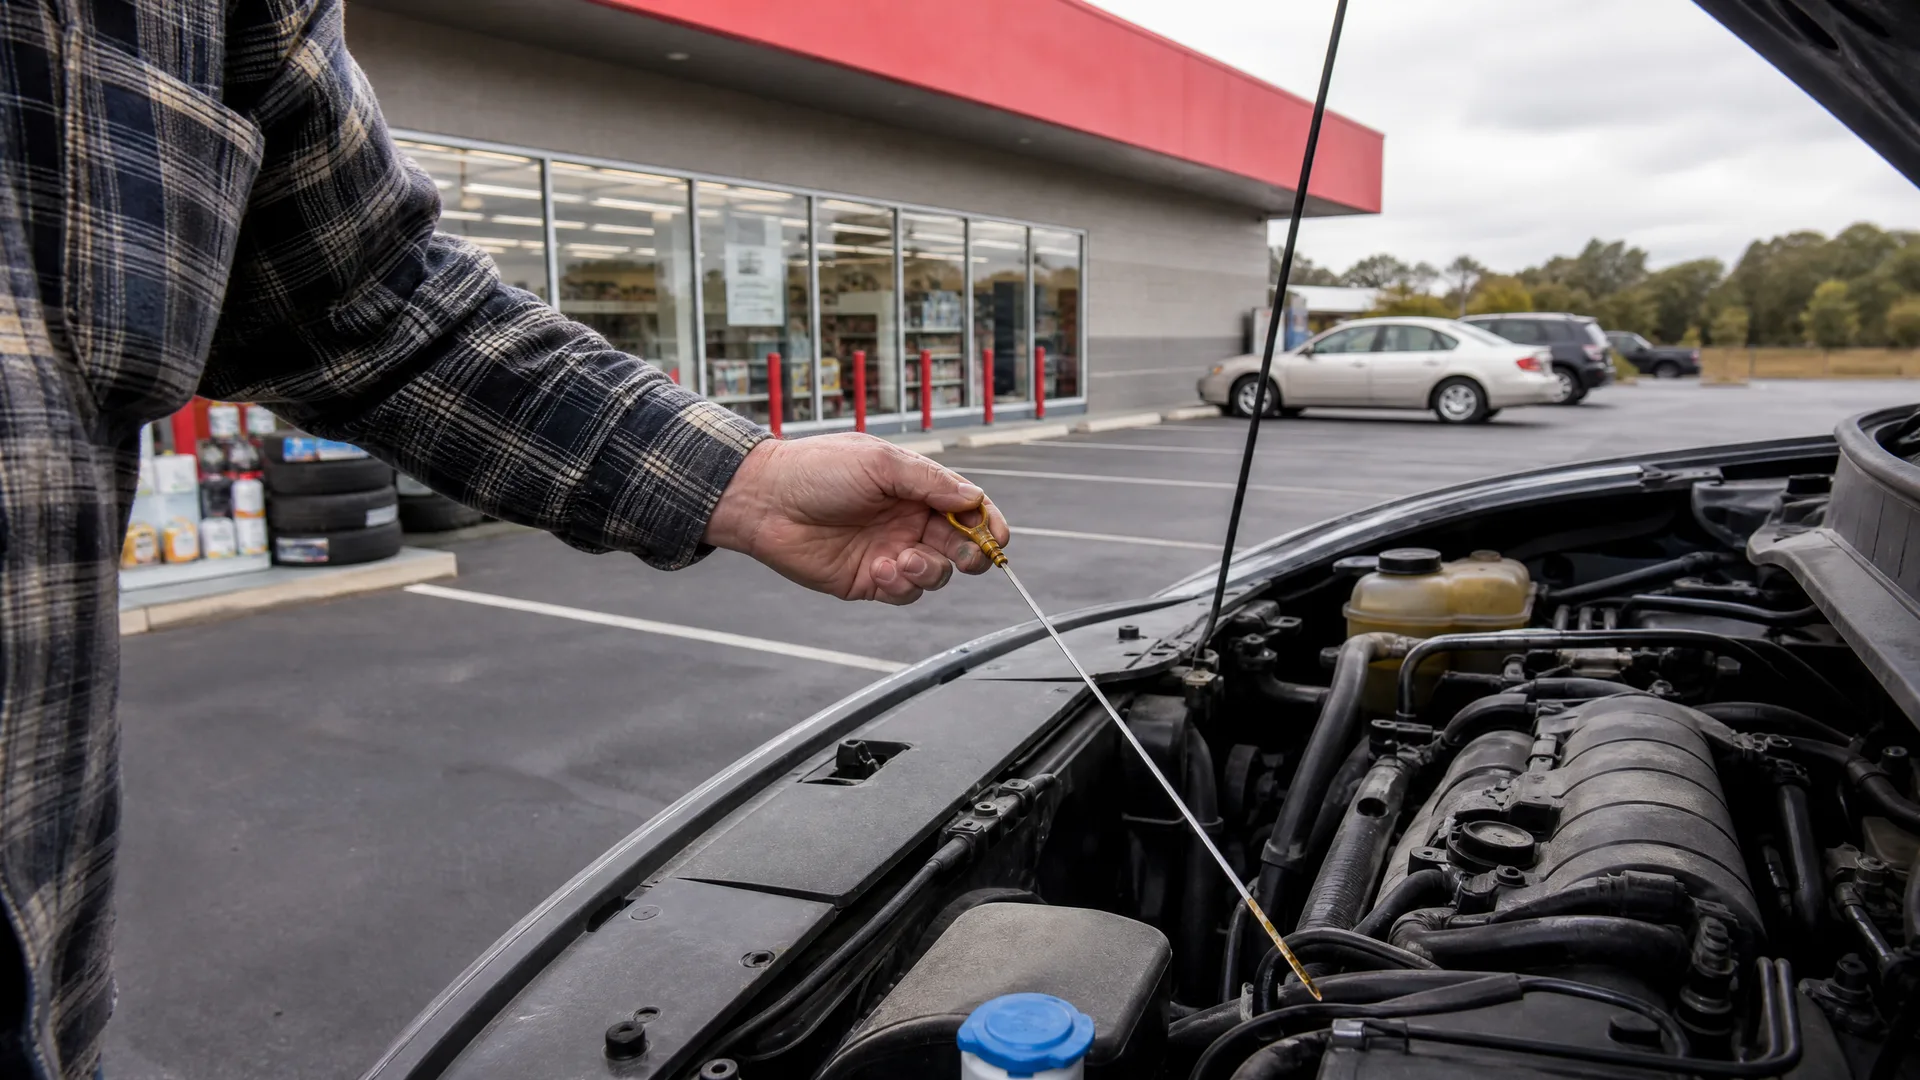
Some Vermont insurers take your word for your annual mileage when you apply or renew. Others ask for an odometer reading, a photo of your dashboard, or access to a telematics app that tracks your driving automatically. The method matters because it affects how much the discount is worth and how easy it is to keep.
If your insurer relies on your estimate, be accurate. Overestimating costs you the discount you deserve. Underestimating can cause problems later if you ever file a claim and the mileage on record doesn't match reality.
If your insurer uses telematics, ask how the device or app works, what it tracks beyond mileage, and whether driving habits like hard braking or time of day driving factor into your rate along with miles driven. Some older drivers prefer not to have that level of tracking, and that's worth asking about before you agree to it.
Either way, ask what proof they'll want if your mileage changes, say you start driving even less after giving up a second car. A policy that doesn't update can leave a discount on the table.
What counts as low mileage is set by each insurer, not the state
Vermont doesn't set a statewide mileage threshold for this discount. Each insurer decides what counts as low enough to qualify, and those numbers differ from company to company. This is the detail most people get wrong. They assume there's a standard cutoff, ask one insurer, get turned down, and give up.
It's worth checking with more than one company, especially if you're near whatever threshold they use. A number that doesn't qualify you at one insurer might easily qualify you at another.
Also ask whether the discount stacks with other discounts you might already have, like one for a defensive driving course or a long history with no claims. Some insurers cap how many discounts apply together, and some don't.
Questions people ask about this
Does a low mileage discount lower my rate more than a mature driver discount in Vermont?
It depends on the insurer, since each one weighs discounts differently and some overlap. Ask your insurer directly how much each discount is worth on your policy and whether having both changes the math. There's no state rule dictating how insurers must stack or prioritize these discounts.
Do I need a special device to prove low mileage to my Vermont insurer?
Not necessarily. Some insurers accept a written estimate or an odometer reading at renewal instead of a tracking device. Ask your insurer which method they use before assuming you'll need to install anything in your car.
What happens if I drive more than I estimated for my Vermont policy?
Your insurer may adjust your premium at renewal once they see your actual mileage, especially if they check your odometer. Tell your insurer if your driving habits change significantly during the policy term rather than waiting for renewal to explain a mismatch.
Can giving up a second car help me qualify for a low mileage discount in Vermont?
It can, since dropping a second car often means putting fewer miles on the one you keep insured. Ask your insurer how removing a vehicle from your policy affects your mileage estimate and whether it changes your discount eligibility.
Will my Vermont insurer lower my rate automatically as I drive less each year after retirement?
No insurer does this automatically. You need to report updated mileage figures to your insurer, usually at renewal, for them to adjust your discount. Ask your agent how often they review mileage and whether you can request a mid-term update if your driving drops suddenly.
See which Vermont insurers reward lower mileage before you commit to a renewal.
Look up your last year of actual driving, using your odometer reading from a year ago if you have it, or your service records if you don't. Call your current insurer and ask what mileage threshold they use for the discount and how they want you to report it. Then get quotes from a couple of other Vermont insurers with that same mileage figure in hand, since thresholds and discount amounts differ by company. Ask each one whether the discount requires an odometer check, a telematics app, or just your estimate. If you've also taken a defensive driving course or have a long claims-free record, ask whether those discounts combine with the low mileage one or replace it.


